Quick answer
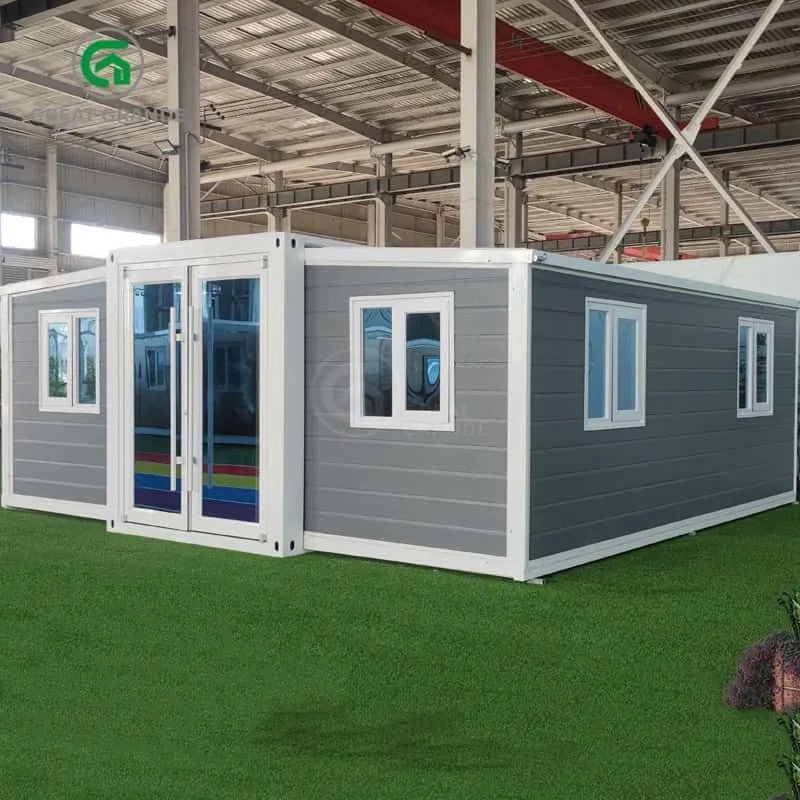
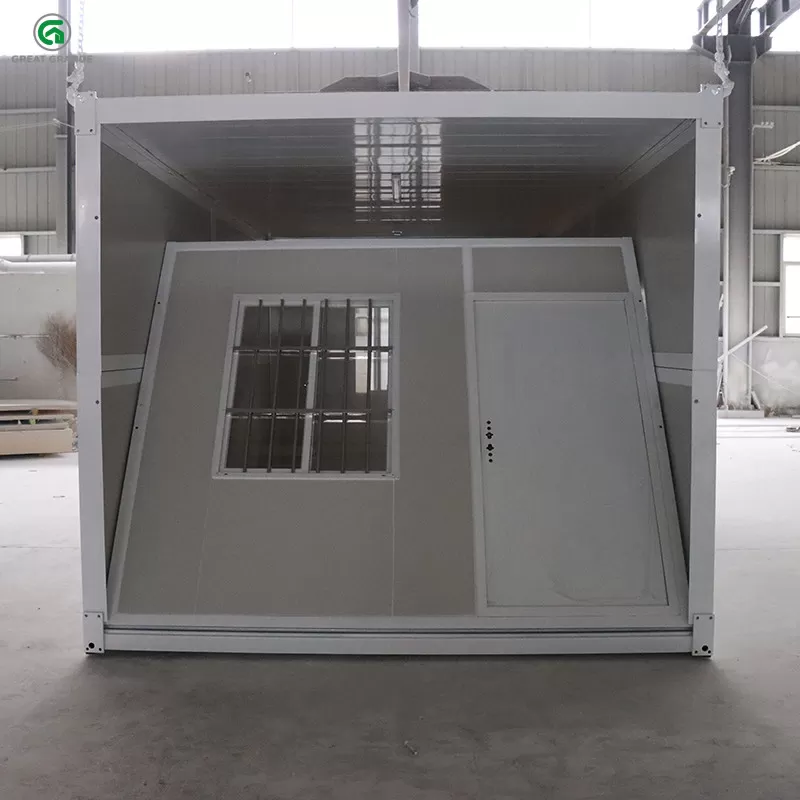
Container Home Insurance: What to Expect and How to Insure One — the essentials: units are built to order, delivered folded to reduce freight, and installed on a simple base. Payment is by bank transfer in full; delivery is port-to-port.
- Confirm local permits/zoning and import requirements for your location first.
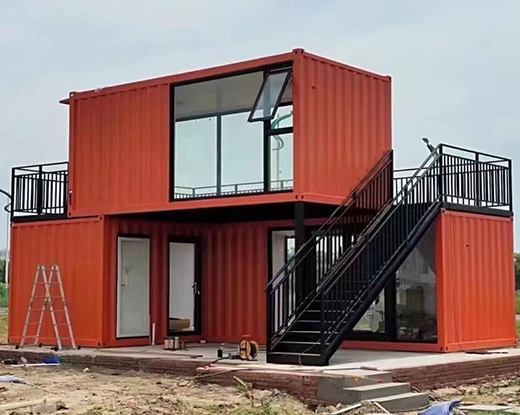
- Choose the size that fits the use: 10FT, 20FT, 40FT, or a double-storey villa.
- Request a quote with your nearest port for exact freight and duties.
Get your quote on WhatsApp — tell us your size and nearest port.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
A factory-built unit has a known spec, which insurers prefer over an improvised conversion. You can show steel thickness, insulation, and electrical layout in writing.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Why a finished unit is easier
A factory-built unit has a known spec, which insurers prefer over an improvised conversion. You can show steel thickness, insulation, and electrical layout in writing.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
They will also ask about the site: access, flood exposure, and whether it is a permanent or seasonal dwelling.
Why a finished unit is easier
A factory-built unit has a known spec, which insurers prefer over an improvised conversion. You can show steel thickness, insulation, and electrical layout in writing.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
An insurer will ask how the unit is founded, how it is fixed against wind, and whether it is on mains services or off-grid. A properly placed, anchored unit is straightforward to cover.
They will also ask about the site: access, flood exposure, and whether it is a permanent or seasonal dwelling.
Why a finished unit is easier
A factory-built unit has a known spec, which insurers prefer over an improvised conversion. You can show steel thickness, insulation, and electrical layout in writing.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Insurers care about structure and site
An insurer will ask how the unit is founded, how it is fixed against wind, and whether it is on mains services or off-grid. A properly placed, anchored unit is straightforward to cover.
They will also ask about the site: access, flood exposure, and whether it is a permanent or seasonal dwelling.
Why a finished unit is easier
A factory-built unit has a known spec, which insurers prefer over an improvised conversion. You can show steel thickness, insulation, and electrical layout in writing.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.
Insurers care about structure and site
An insurer will ask how the unit is founded, how it is fixed against wind, and whether it is on mains services or off-grid. A properly placed, anchored unit is straightforward to cover.
They will also ask about the site: access, flood exposure, and whether it is a permanent or seasonal dwelling.
Why a finished unit is easier
A factory-built unit has a known spec, which insurers prefer over an improvised conversion. You can show steel thickness, insulation, and electrical layout in writing.
Documents make underwriting faster. Get your spec sheet from us before you shop for cover.
Mains vs off-grid
A unit on mains power and water is insured like a standard home. An off-grid unit can still be covered, but expect more questions about your power and water systems.
Tell the insurer exactly how the unit is set up; under-insuring by omission is the common mistake.
What affects the premium
Location, reconstruction value, use (home, rental, or business), and any additional structures all move the premium.
Insure for the true replacement cost of the unit plus shipping and site works, not just the factory price.
Payment, plainly
We do not offer financing. Payment for the unit is by bank transfer in full, port-to-port. Insurance is yours to arrange locally.
The takeaway
Insure a finished, properly anchored container home as you would any steel dwelling. Keep the spec sheet, tell the insurer how it is set up, and cover from day one.